

If you run a high-risk business, you already know that getting a merchant account is never as “instant” as promised.
Approval can feel like a waiting game—weeks spent on hold, endless questions about your business model, and the looming threat of higher fees just for operating in a riskier category.
Most payment processors treat high-risk industries like a hot potato.
If you’re in CBD, credit repair, nutraceuticals, adult, or anything the banks don’t love, you’ll hit roadblocks: rejections, rolling reserves, or a flat-out refusal to even review your application. That’s why instant approval high-risk merchant account services matter.
This guide cuts through the noise. I reviewed the leading providers for instant approval merchant accounts—looking at how fast they move, how well they handle fraud, what support you actually get, and how clear their pricing is (because surprise fees are nobody’s idea of fun).
I’m not an insider on the payments side, but I’ve spent years working in retail and ecommerce—long enough to know what keeps business owners up at night. If you need payment processing you can actually rely on, you’re in the right place.
Why Trust Our Software Recommendations
6,700+
Reviews
20
Industry experts
16+
Evaluation factors
14
Years
Our team has been testing and reviewing software since 2012. As retail leaders ourselves, we know how difficult—and important—it is to choose the right software.
For this guide, we evaluated tools using hands-on testing and independent research, scoring tools using our selection criteria.
Our reviews reflect our independent judgment—not a sales pitch.
High-Risk Merchant Account Instant Approval Comparison Table
Let’s see how these options stack up on pricing, trial info, and specialties so you know what’s what.
| Tool | Best For | Trial Info | Price | ||
|---|---|---|---|---|---|
| 1 | Best for quick approval times | Not available | From $14.99/month | Website | |
| 2 | Best for 1,500+ vertical approvals | Not available | Pricing upon request | Website | |
| 3 | Best for chargeback protection | Free demo available | From $50/month | Website | |
| 4 | Best for MATCH-listed merchant recovery | Not available | From IC + 1.10% | Website | |
| 5 | Best for restricted verticals with no setup costs | Not available | Pricing upon request | Website | |
| 6 | Best for fast approval with multi-bank routing | Not available | From $29/month | Website | |
| 7 | Best for ecommerce businesses | Free demo available | From $25/month | Website | |
| 8 | Best for travel and hospitality | Not available | From $15/month | Website | |
| 9 | Best for omnichannel high-risk retail boarding | Not available | From 3.25% per transaction | Website | |
| 10 | Best for CBD and vape merchant boarding | Not available | From $2.6% + $0.15/transaction | Website |


The Best High-Risk Instant Approval Merchant Account Provider Reviews
Below you’ll find my take on each high-risk instant approval merchant account provider that made the shortlist.
I’ve focused on what actually sets them apart—where they fit best, what they handle well, and what to watch out for—so you can quickly zero in on a service that won’t slow you down.

Host Merchant Services homepage lets merchants request a quote to get started. Host Merchant Services is a merchant account provider built for high-risk retail verticals—including CBD, firearms, vape, adult content, and nutraceuticals—offering interchange-plus pricing, omnichannel payment processing, and fast underwriting through alternate acquiring bank partners.
Who Is Host Merchant Services Best For?
Host Merchant Services is a strong fit for moderate-risk retail businesses that need fast underwriting and transparent pricing without long-term contracts.
Why I Picked Host Merchant Services
Host Merchant Services earns its spot on my shortlist because its 24–48 hour underwriting window is one of the fastest I've seen for high-risk retail verticals like CBD, vape, and firearms. I picked it specifically for merchants who've been turned away by Stripe or Square and need a real acquiring relationship fast. HMS routes these accounts through alternate bank partners, so verticals that aggregators flat-out reject can get approved and processing within two business days.
Host Merchant Services Key Features
- Interchange-plus pricing: HMS publishes its cost-plus rate structure openly, so you can see exactly what you're paying above interchange on every transaction.
- Multi-currency support: Accepts payments in 135+ currencies, making it viable for retailers serving international customers.
- Free POS hardware: Approximately 98% of qualified applicants receive terminal hardware at no cost, covering devices like Clover, PAX, and Ingenico.
- Month-to-month contracts: No long-term commitment is required, so you're not locked in if your processing needs change.
Host Merchant Services Integrations
Host Merchant Services offers integrations with seven POS systems, including Clover, Korona, SwipeSimple, Dejavoo, Valor Paytech, Vital, and Bonsai, plus Shopify, WooCommerce, QuickBooks Online, NetSuite Payments, Authorize.Net, and Transaction Express. REST APIs, SDKs, plugins, and hosted checkout pages support custom integrations.
Pros and Cons
Pros:
- Free POS hardware for qualified applicants
- Transparent, published interchange-plus pricing
- Approval within 24–48 hours for most
Cons:
- No automation for chargeback representment
- Does not support MATCH-listed merchants
Learn more about Host Merchant Services:
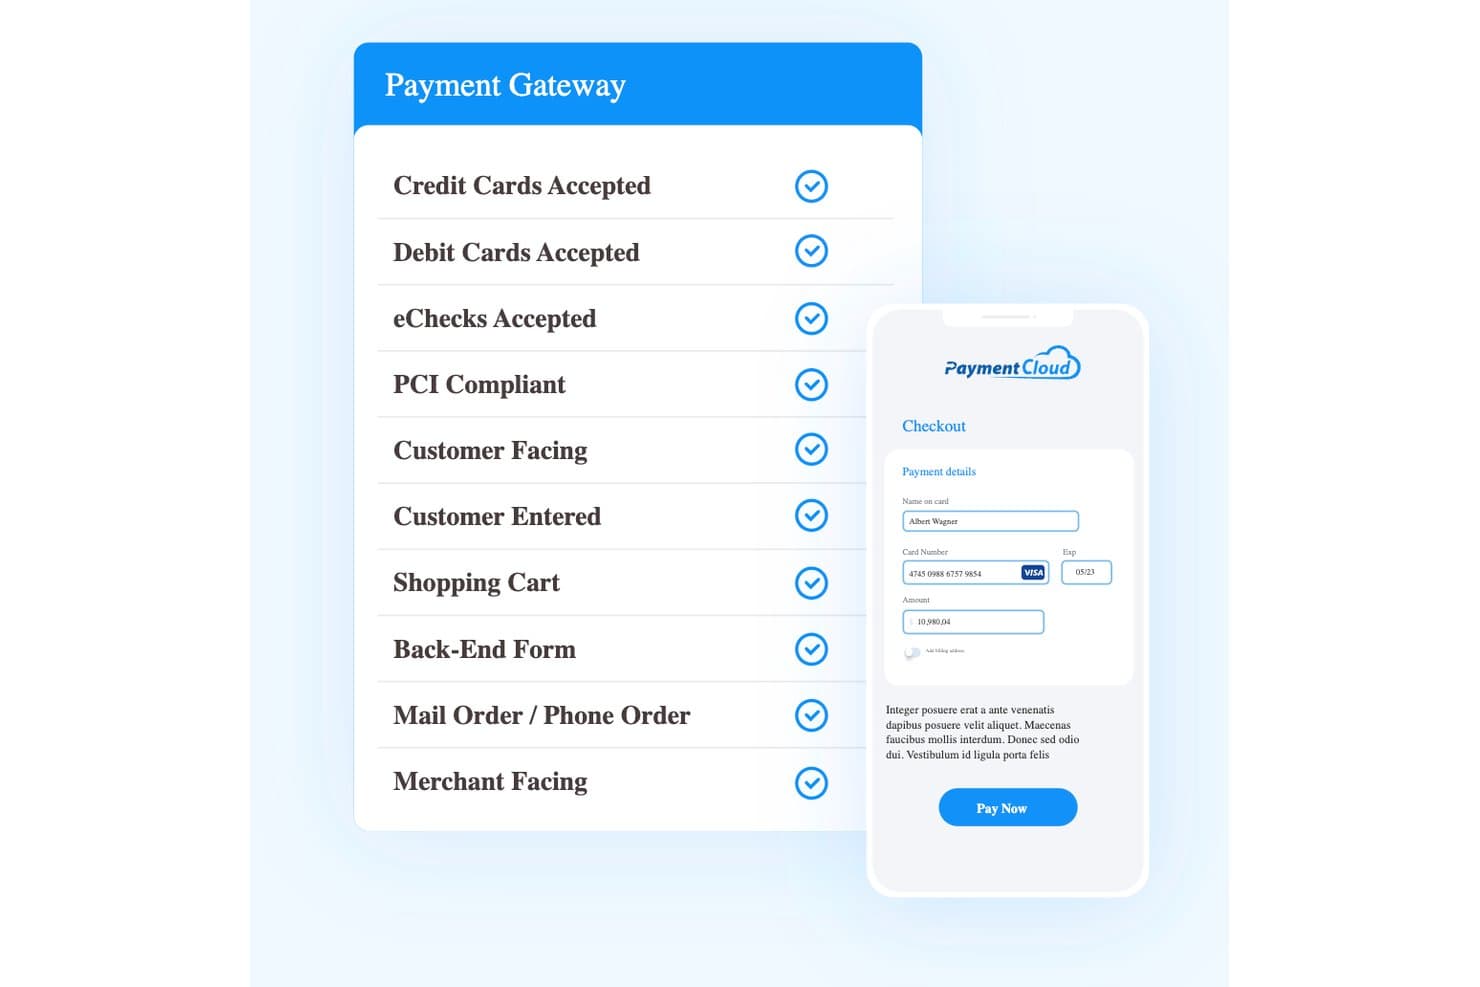
PaymentCloud supports credit, debit, eChecks, and multiple order types. PaymentCloud is a high-risk merchant account provider that combines multi-bank underwriting, omnichannel payment processing, and chargeback management tools to serve businesses in restricted or hard-to-place verticals.
Who Is PaymentCloud Best For?
- PaymentCloud is a good fit for US-based merchants in hard-to-place industries that need flexible underwriting after being declined by mainstream processors.
Why I Picked PaymentCloud
PaymentCloud earns its spot on my shortlist because of its breadth of 1,500+ approved verticals, covering everything from CBD to online pharmacy and bail bonds. I like that its multi-bank underwriting network lets declined applications route to alternative banks automatically, which is a real advantage if you've already been turned away by Stripe or Square. Its chargeback tooling, including Kount and Disputifier integrations, adds meaningful protection in categories where chargebacks are the norm.
PaymentCloud Key Features
- Omnichannel payment acceptance: Supports in-person EMV terminals, virtual terminal (MOTO), online checkout, ACH/eCheck, and recurring billing from a single merchant account.
- Dedicated account manager: Each merchant is assigned a vertical-specific account manager who guides onboarding and provides ongoing US-based support.
- Rolling reserve management: Structures rolling reserves (typically 5%–10% of volume) with release schedules of 90–180 days to help merchants plan around withheld funds.
- 3D Secure authentication: Adds a cardholder verification layer at checkout to reduce fraud-related chargebacks on card-not-present transactions.
PaymentCloud Integrations
PaymentCloud offers 10+ documented ecommerce integrations, including Shopify, WooCommerce, BigCommerce, Magento, and Ecwid. It also supports Authorize.Net, NMI, USAePay, and POS hardware from Clover, Dejavoo, Ingenico, Pax, SwipeSimple, and Verifone.
Pros and Cons
Pros:
- Dedicated vertical-specific account managers
- Multi-bank network increases approval odds
- Boards 1,500+ high-risk business verticals
Cons:
- Early termination fees in many contracts
- Monthly account fees always apply
Learn more about PaymentCloud:
EMB offers chargeback tools and support to reduce disputes and ensure cash flow. EMB is a high-risk merchant account provider that specializes in underwriting hard-to-place businesses, offering card-present and card-not-present processing, a proprietary payment gateway, ACH and cryptocurrency support, and chargeback mitigation tools.
Who Is EMB Best For?
- EMB is a good fit for dispute-prone merchants that need proactive chargeback alerts and prevention alongside high-risk processing.
Why I Picked EMB
I picked EMB as one of the best because its chargeback protection setup is genuinely more layered than anything else I've seen in this category. It runs simultaneous integrations with both Ethoca and Verifi, meaning dispute alerts come in from two separate networks before a chargeback is ever formally filed. On top of that, EMB's proprietary alert system adds a third layer, which the company says reduces chargebacks by 25%.
EMB Key Features
- 99% approval rate underwriting: EMB underwrites merchants across 20+ high-risk verticals, including MATCH/TMF-listed businesses and those with prior processor terminations.
- ACH and eCheck processing: Merchants can accept payments via checks-by-web, checks-by-phone, and mobile check processing through EMB's iCheck tool.
- Cryptocurrency payment acceptance: EMB supports Bitcoin and other cryptocurrency payments with automatic conversion to fiat currency at the time of transaction.
- Multi-gateway compatibility: EMB connects with Authorize.Net, NMI, eProcessing Network, and its own proprietary gateway, extending compatibility to 150+ shopping carts.
EMB Integrations
EMB lists integrations with Shopify, WooCommerce, BigCommerce, Wix, Volusion, PrestaShop, Authorize.Net, NMI, eProcessing Network, and 1st Pay. NMI extends compatibility to 150+ shopping carts.
Pros and Cons
Pros:
- Supports both card-present and card-not-present sales
- High approval rates for terminated merchants
- Chargeback alerts from three independent systems
Cons:
- Contracts include early termination fees
- No transparent transaction pricing online
Learn more about EMB:
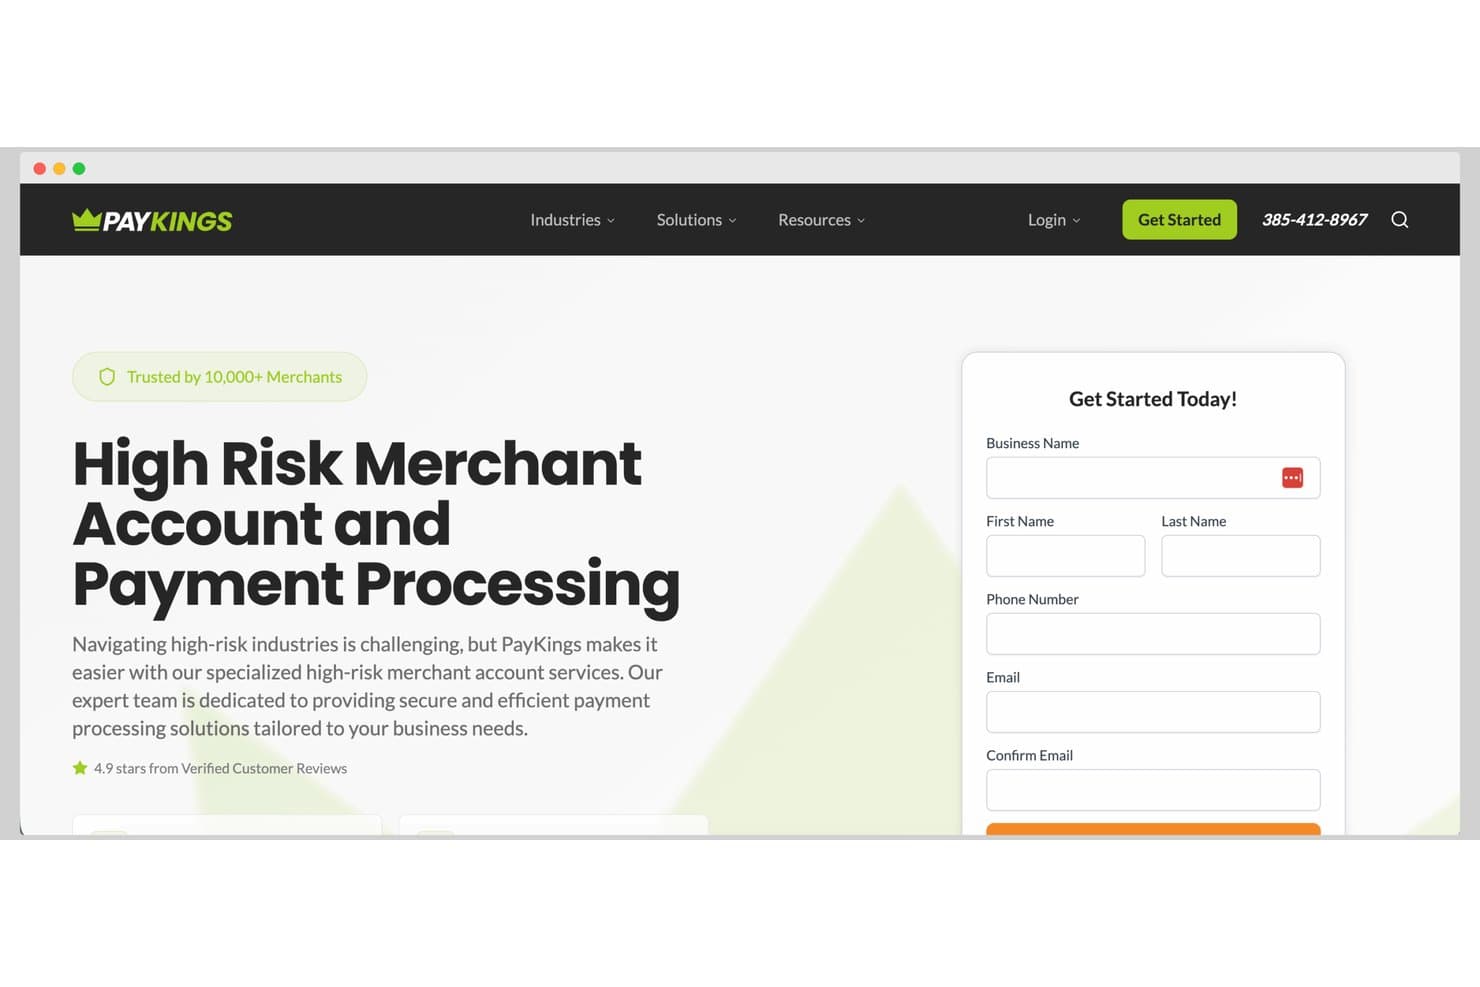
PayKings lets merchants apply for high-risk payment processing instantly online. PayKings is a high-risk merchant account provider that underwrites 50+ restricted and high-chargeback verticals with interchange-plus pricing, integrated chargeback management, and omnichannel payment processing across in-store, ecommerce, and ACH rails.
Who Is PayKings Best For?
- PayKings is a good fit for merchants in heavily regulated industries like CBD, adult, or online gambling that need specialized underwriting.
Why I Picked PayKings
If your account was terminated by a previous processor, PayKings reviews your case individually and routes you through one of its 20+ acquiring bank relationships to find the right fit. I also like that chargeback alerts and dispute management are built directly into the merchant account, which matters when you're in a high-chargeback vertical and can't afford a reactive approach to disputes.
PayKings Key Features
- Interchange-plus pricing tiers: Three published pricing tiers—Starter, Growth, and Enterprise—scale with monthly processing volume, with rates starting at interchange + 1.10%.
- ACH and eCheck processing: A lower-cost payment rail for subscriptions and B2B transactions, reducing chargeback exposure compared to card-based payments.
- 3D Secure 2.0 authentication: Shifts fraud-chargeback liability to the issuing bank on authenticated card-not-present transactions across major card networks.
- Multi-bank routing network: Routes each merchant account through one of 20+ acquiring bank relationships based on industry type and risk profile.
PayKings Integrations
PayKings offers integrations with Shopify, WooCommerce, Magento, Authorize.net, NMI, and USAePay, plus a REST API for custom connections.
Pros and Cons
Pros:
- Integrated AI fraud and chargeback management
- Fast approval for most high-risk accounts
- Accepts MATCH-listed and previously terminated merchants
Cons:
- Application-based process may require extensive documentation
- Final account terms set by acquiring bank
Learn more about PayKings: Best for restricted verticals with no setup costs
- Not available
- Pricing upon request
SecureGlobalPay collects key business details to fast-track merchant approval. SecureGlobalPay is a high-risk merchant account provider that serves restricted and hard-to-place verticals with omnichannel payment processing, a proprietary PCI-compliant gateway, multi-MID load balancing, and both domestic and offshore acquiring bank options.
Who Is SecureGlobalPay Best For?
- SecureGlobalPay is a good fit for international or high-volume merchants that need offshore acquiring, multi-currency processing, or multiple MIDs.
Why I Picked SecureGlobalPay
SecureGlobalPay earns its spot on my shortlist because it removes common financial barriers to getting started—no application fee, no setup fee, no monthly fee, and free Clover POS hardware shipped to qualifying merchants. I picked it specifically for restricted-vertical operators who've been turned away elsewhere through both domestic and offshore acquiring banks. The multi-MID load balancing is what really sets it apart: it intelligently splits transaction volume across multiple merchant IDs to keep chargeback ratios below Visa and Mastercard monitoring thresholds.
SecureGlobalPay Key Features
- Offshore acquiring bank access: Connects merchants to international acquiring banks when domestic options aren't available, supporting the most restricted verticals.
- Chargebacks911 partnership: Built-in access to Chargebacks911 for automated dispute management and chargeback representment.
- Next-day funding: Settles funds within 24 hours of batch submission, including American Express transactions.
- Dual pricing and surcharging programs: Lets qualifying merchants pass card processing costs to customers or offer a cash discount at checkout.
SecureGlobalPay Integrations
SecureGlobalPay offers integrations with Shopify, WooCommerce, QuickBooks, Clover, Dejavoo, NMI, Authorize.Net, and Chargebacks911. It claims 125+ shopping cart and 200+ platform integrations, plus a REST API and SDK for custom connections.
Pros and Cons
Pros:
- Proprietary PCI-compliant gateway is included
- Free POS hardware for approved accounts
- Approves MATCH-listed and terminated merchants
Cons:
- Approval takes 2–5 business days
- No published rates or fee schedule
Learn more about SecureGlobalPay:
Zen Payments supports high-risk merchant processing with same-day approvals. Zen Payments is a high-risk merchant account provider that combines multi-bank routing across 15+ acquiring banks with omnichannel payment processing, chargeback mitigation tools, and integrations for major ecommerce platforms like Shopify, WooCommerce, and BigCommerce.
Who Is Zen Payments Best For?
- Zen Payments is a good fit for US ecommerce and subscription merchants that need fast underwriting alongside robust fraud and chargeback tools.
Why I Picked Zen Payments
I picked Zen Payments as one of the best because its multi-bank routing across 15+ acquiring banks is what actually makes fast approval possible, not just a marketing claim. If you've been terminated or declined, Zen matches your application to whichever bank in its network is most likely to approve your vertical, whether that's CBD, nutraceuticals, or adult content. I also like that it accepts MATCH-listed merchants and credit scores as low as 500.
Zen Payments Key Features
- Verifi CDRN and Ethoca alert integration: Sends chargeback alerts 24–72 hours before a dispute is formally filed, giving you time to issue a refund and avoid a chargeback.
- 3DS 2.0 authentication: Adds a real-time, risk-based authentication layer at checkout to verify cardholders and reduce fraud-related disputes.
- Virtual terminal: Lets you key in card details manually for phone, mail, or in-person orders without a physical card reader.
- Interchange-plus pricing: Breaks out the card network's base rate from Zen Payments' markup, so you can see exactly what each component of your processing cost covers.
Zen Payments Integrations
Zen Payments offers 20+ documented integrations, including Shopify, WooCommerce, BigCommerce, NMI, Authorize.Net, Chargebee, Recurly, Verifi, and Ethoca. REST APIs and JavaScript, Python, Ruby, PHP, and Java SDKs support custom integrations.
Pros and Cons
Pros:
- Approval decisions often within 24–48 hours
- Offers real-time chargeback alert integrations
- Approves MATCH-listed and terminated merchants
Cons:
- "Instant approval" not always actual approval
- Fund holds reported after sudden shutdowns
Learn more about Zen Payments:
Easy Pay Direct ensures stability with routing across multiple accounts. Easy Pay Direct is a high-risk merchant account provider that pairs dedicated merchant accounts with its proprietary gateway, offering multi-MID load balancing, chargeback mitigation tools, and 500+ ecommerce integrations across platforms like Shopify, WooCommerce, and BigCommerce.
Who Is Easy Pay Direct Best For?
Easy Pay Direct is a good fit for high-volume ecommerce and subscription businesses that need multi-MID routing to reduce payment disruptions.Why I Picked Easy Pay Direct
Easy Pay Direct earns its spot on my shortlist because its multi-MID load balancing is something I haven't seen matched elsewhere in the high-risk space. For ecommerce businesses running Shopify or WooCommerce, the gateway automatically routes transactions across multiple merchant accounts, so a spike in chargebacks on one MID doesn't freeze your entire operation. I also value that EPD underwrites merchants upfront across 20+ high-risk verticals, which means CBD or nutraceutical stores get a stable account from day one rather than a PayFac approval that quietly collapses later.
Easy Pay Direct Key Features
- 30+ acquiring bank network: EPD places your account with one of 30+ specialized acquiring banks matched to your specific vertical, rather than routing all merchants through a single bank.
- ACH/eCheck processing: Accept ACH payments at 1% + $0.29 per transaction through the same gateway used for card payments, with no separate account needed.
- Interchange-plus pricing: Merchants processing $50,000 or more per month can access interchange-plus pricing for a more transparent, lower effective rate.
- Dedicated account manager: Every merchant gets an assigned human specialist—not a support queue—for direct help with account issues, underwriting questions, and rate reviews.
Easy Pay Direct Integrations
Easy Pay Direct advertises 500+ integrations, including Shopify, WooCommerce, BigCommerce, Magento, ClickFunnels, Kajabi, Teachable, Thinkific, Clover, and GoHighLevel. It also supports a REST API, webhooks, TypeScript and Python SDKs, and Zapier.
Pros and Cons
Pros:
- Chargeback alerts and representment included
- Human underwriting supports true high-risk verticals
- Multi-MID routing reduces risk of account freezes
Cons:
- Approval takes 1–4 business days
- Gateway fee required for all accounts
Learn more about Easy Pay Direct:
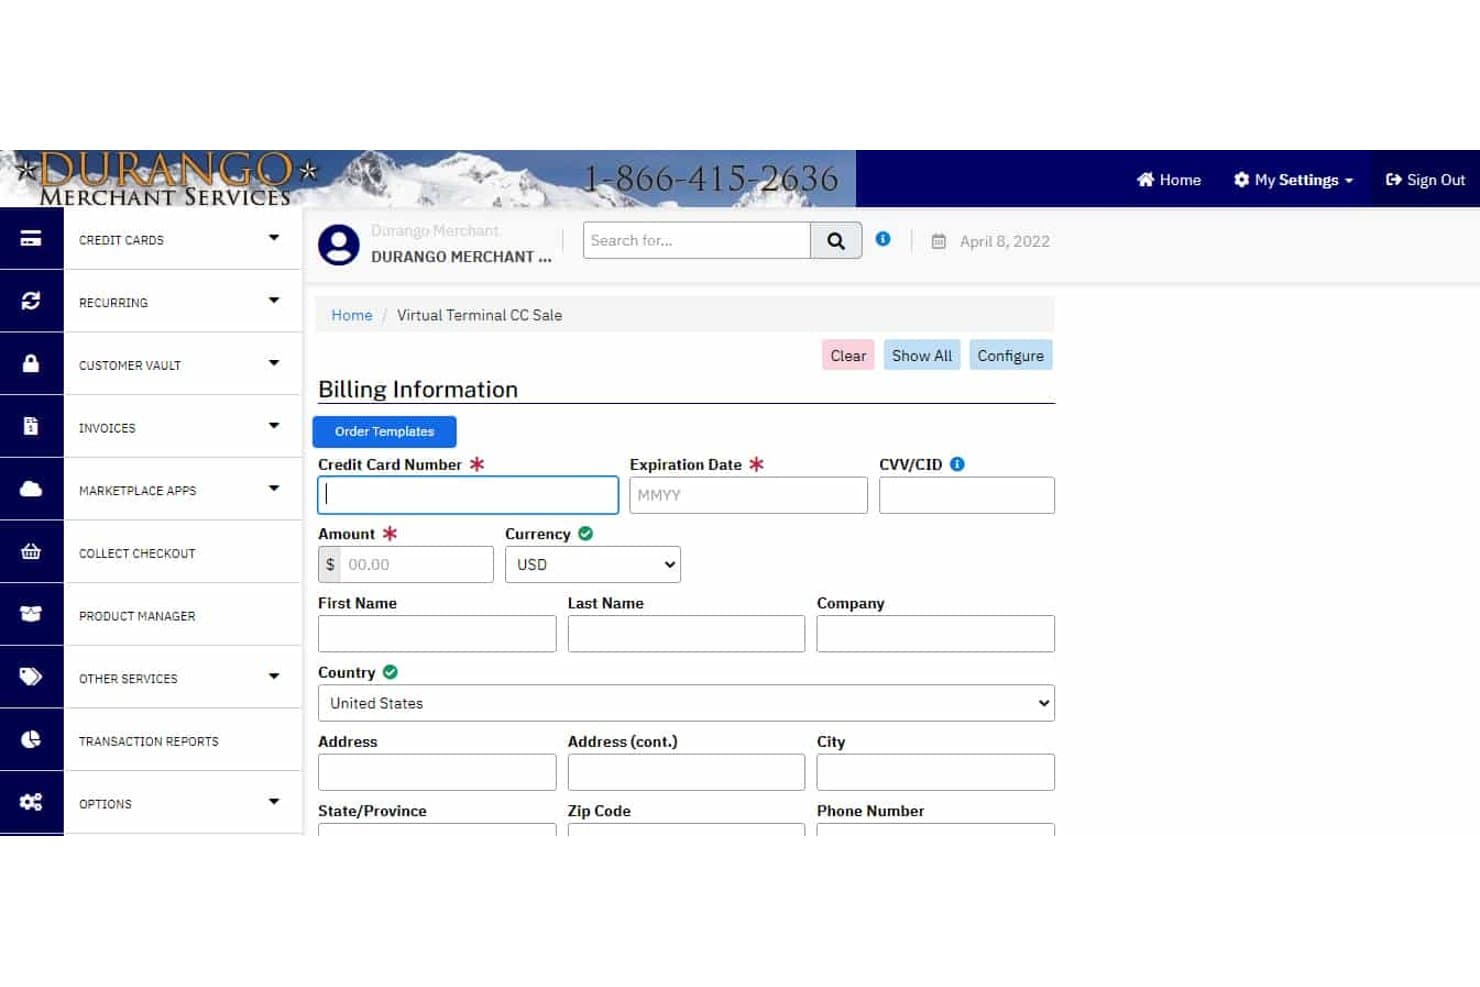
Durango Merchant Services lets users process card payments via virtual terminal. Durango Merchant Services is a high-risk merchant account provider that specializes in payment processing for restricted and hard-to-place verticals, offering omnichannel transaction support, multi-bank acquiring, chargeback mitigation tools, and a proprietary gateway with multi-currency and recurring billing capabilities.
Who Is Durango Merchant Services Best For?
Durango Merchant Services is a good fit for established, high-volume or international merchants that need multi-bank routing and cross-border processing.Why I Picked Durango Merchant Services
Durango Merchant Services earns its spot on my shortlist because travel and hospitality merchants face a unique combination of high chargeback rates, multi-currency volume, and fraud exposure that most processors won't touch. I like that Durango's travel-specific underwriting pairs 3-D Secure 2.0/2.2 with its proprietary Fraud Deflect tool, which catches friendly fraud in real time before disputes become chargebacks. Its multi-MID load balancing via the ATRI routing engine also means your processing volume stays below Visa and Mastercard chargeback thresholds, even during high-season booking surges.
Durango Merchant Services Key Features
- Merchant Recovery Services: A dedicated onboarding path for merchants terminated by Stripe, Square, PayPal, or Shopify Payments, designed to restore processing quickly.
- Multi-MID load balancing: Splits processing volume across multiple merchant IDs to keep chargeback ratios below Visa and Mastercard monitoring thresholds.
- ACH and eCheck processing: Supports direct bank transfers with check verification alongside standard card payments for flexible payment acceptance.
- ATRI cascading routing: Automatically routes declined transactions across multiple acquiring banks to maximize approval rates for high-risk volume.
Durango Merchant Services Integrations
Durango Merchant Services supports integrations with 150+ shopping carts, including Shopify, WooCommerce, Magento, BigCommerce, Salesforce, Zoho, Authorize.Net, NMI, FluidPay, and Inovio. REST and JSON APIs, hosted checkout, and iOS and Android SDKs support custom integrations.
Pros and Cons
Pros:
- Offers proprietary friendly fraud prevention
- Multi-MID load balancing for chargeback control
- Onboards most high-risk travel businesses
Cons:
- Monthly account fees always apply
- No true instant approval automation
Learn more about Durango Merchant Services: Best for omnichannel high-risk retail boarding
- Not available
- From 3.25% per transaction
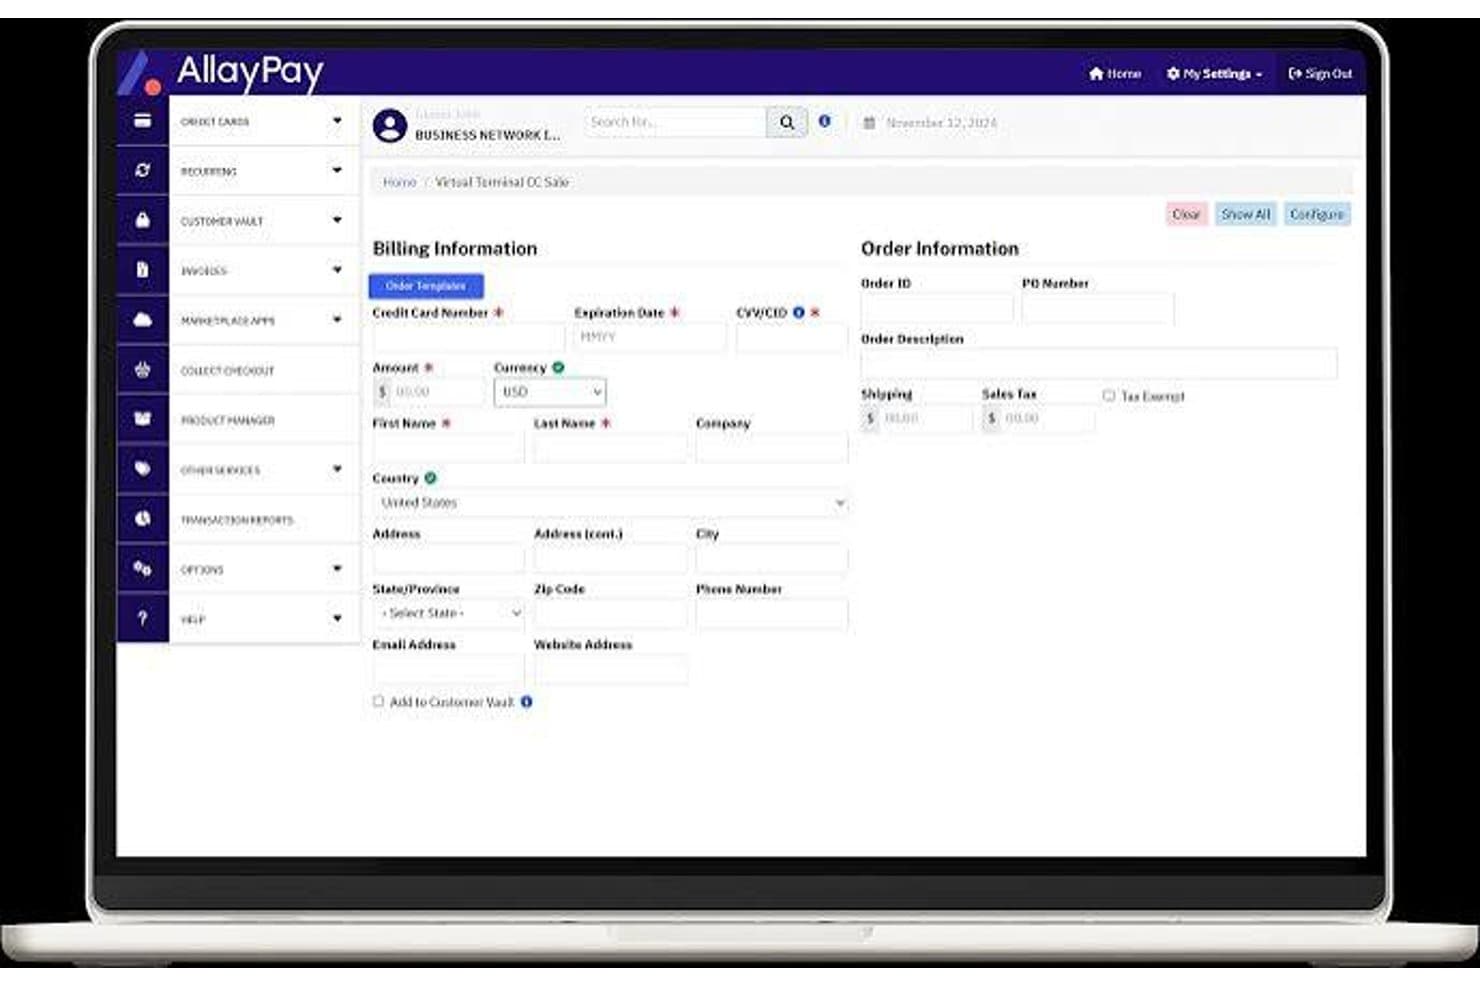
Access several virtual terminals and payment gateways with AllayPay. AllayPay is a high-risk merchant account provider that supports card-present, ecommerce, and MOTO processing across restricted verticals like CBD, vape, adult content, and nutraceuticals.
Who Is AllayPay Best For?
AllayPay is a good fit for merchants in tightly regulated niches like CBD, hemp, vape, and peptides that need specialized underwriting.
Why I Picked AllayPay
AllayPay earns its spot on my shortlist because it's one of the few providers that can board a CBD retailer, a vape shop, and a firearms dealer under a single account framework that covers card-present, ecommerce, and MOTO processing. I particularly like that it explicitly accepts MATCH/TMF-listed merchants, which matters when your previous processor terminated your account without warning. Same-day approval is advertised across every vertical, and for omnichannel retail operators juggling a Shopify storefront alongside a physical Clover terminal, that speed is real.
AllayPay Key Features
- MATCH/TMF merchant acceptance: AllayPay reviews and boards merchants who appear on the MATCH/TMF terminated merchant list.
- Multiple gateway options: Merchants choose from Authorize.net, NMI, or FluidPay to connect with their existing tech stack.
- Surcharging and dual pricing programs: AllayPay offers built-in surcharging, cash discount, and dual pricing configurations at the account level.
- QuickBooks Online integration: Payments sync directly to QuickBooks Online with automatic invoice-to-paid status updates.
AllayPay Integrations
AllayPay supports integrations with Shopify, WooCommerce, BigCommerce, Clover, LightSpeed, CoreSTORE, Quantic, Authorize.net, NMI, FluidPay, QuickBooks Online, Salesforce, and GoHighLevel. It also references an open API for custom integrations.
Pros and Cons
Pros:
- No setup or early termination fees
- Same-day account approvals advertised for all categories
- Accepts MATCH/TMF merchants in restricted verticals
Cons:
- Very few independent user reviews available
- Reserve requirements not fully disclosed upfront
Learn more about AllayPay: Best for CBD and vape merchant boarding
- Not available
- From $2.6% + $0.15/transaction
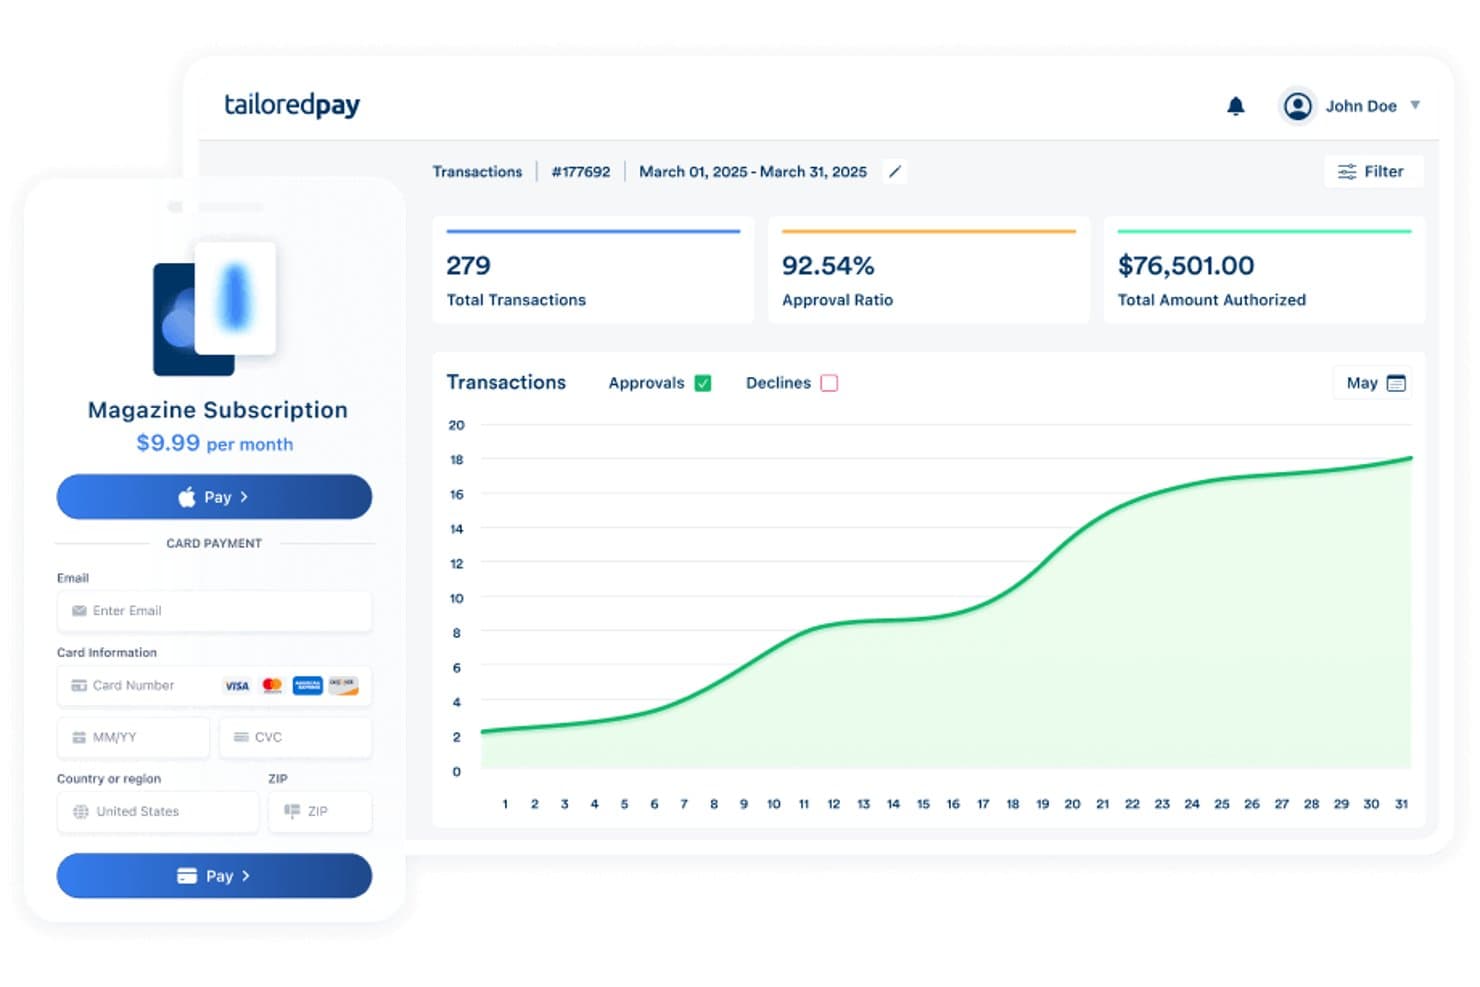
Manage subscriptions and other services through Tailored Pay. Tailored Pay is a high-risk merchant account provider that specializes in underwriting restricted and declined-merchant verticals, offering card-present, card-not-present, ACH, and virtual terminal processing across 100+ industries.
Who Is Tailored Pay Best For?
- Tailored Pay is a good fit for US-based merchants in restricted industries that want fast underwriting and flexible ecommerce integrations.
Why I Picked Tailored Pay
I've included Tailored Pay in my top picks because it runs real underwriting upfront, so you're not boarded and then quietly shut down later. Its high approval rates across verticals like CBD, firearms, and vape, combined with 24-hour underwriting decisions, makes it a reliable option when you need processing reinstated fast.
Tailored Pay Key Features
- ACH and eCheck processing: Supports bank-to-bank transfers with recurring billing, same-day ACH for eligible accounts, and lower per-transaction fees than card payments.
- Virtual terminal: Lets you manually key in transactions from phone, email, or MOTO orders through a browser-based interface without additional hardware.
- Ecommerce platform integrations: Connects natively with Shopify, WooCommerce, Wix, Magento, and several other platforms via Authorize.Net, NMI, and USAePay gateways.
- Rate match guarantee: Matches or beats any comparable competitor rate when you provide proof of a lower quote.
Tailored Pay Integrations
Tailored Pay integrations include Shopify, WooCommerce, Wix, Magento, Authorize.Net, NMI, USAePay, QuickBooks, OpenCart, and PrestaShop. It also offers REST APIs for custom connections.
Pros and Cons
Pros:
- No application or setup fees required
- Approves most high-risk retail categories quickly
- Works with MATCH list and terminated merchants
Cons:
- Charges for chargeback alerts and gateway use
- Only available to US-registered businesses
Learn more about Tailored Pay:
Other High Risk Merchant Services
You’ve seen the top picks, now check out a few others we also like.
- 11CCBillBest for subscription vertical approvals
- 12CorepayBest for multi-MID load balancing across banks
- 13Payment CloudBest for small businesses
- 14SOAR PaymentsBest for tactical gear businesses
- 15High Risk PayBest for diverse payment options
- 16Webpays Best for international clients
- 17ECS PaymentsBest for data security compliance
How I Evaluate High Risk Merchant Accounts
I split my evaluation into two layers: the baseline underwriting, chargeback, and fraud tools a provider must offer, and the differentiators—like MID load balancing and reserve flexibility—that separate the best from the rest.
Core Functionality (Table Stakes for This List)
When I'm selecting tools for my list, I rank each one on a scale from 0 (does not offer the functionality) to 5 (excels in this area) for each core functionality listed below. I then calculate the tool's total score into a percentage, using 65% as a benchmark to help assess its overall fit for the list.
- High-Risk Underwriting: I check which verticals each provider approves—CBD, firearms, nutraceuticals, adult, subscriptions—and whether they'll consider merchants with prior terminations or no processing history.
- Card Processing & Gateway: The provider should support major card brands across both card-present and card-not-present channels through an integrated gateway, not a patchwork of third-party connections.
- Chargeback Management: I look for multi-network alert coverage through services like Ethoca and Verifi, plus representment support that helps merchants stay below monitoring program thresholds.
- Fraud Prevention & PCI Compliance: Providers earn higher marks when they layer AVS, CVV, 3D Secure, velocity filters, and tokenization on top of PCI-DSS Level 1 compliance rather than offering bare-minimum screening.
- Multi-Currency & Global Acquiring: I evaluate the breadth of acquiring bank relationships and currency support, since merchants in high-risk verticals often need offshore redundancy to avoid single-bank exposure.
- Retail/Ecommerce Integrations: Compatibility with platforms like Shopify, WooCommerce, and Magento matters, along with POS support for brick-and-mortar merchants who also sell online.
Once I have a list of tools that meet the criteria, I consider what sets each platform apart.
Differentiating Factors (What Sets Vendors Apart)
Here's how I compare and contrast different vendors:
Standout Features
Cascading payment routing is a big one—I look for providers that automatically reroute declined transactions across multiple acquiring banks, which directly lifts approval rates for merchants in verticals like nutraceuticals or subscriptions. Load-balanced MIDs go hand in hand with this, splitting volume so no single MID breaches Visa or Mastercard chargeback monitoring thresholds. I also evaluate chargeback mitigation depth, specifically whether a provider offers alert integrations with both Ethoca and Verifi plus representment automation rather than basic dispute notifications.
Beyond Features
I evaluate fee transparency closely—specifically whether a provider discloses rolling reserve percentages, release timelines, and early termination penalties upfront or buries them in contract addenda. A CBD merchant locked into a multi-year agreement with undisclosed liquidated damages faces real financial risk if they need to switch processors. I also check whether the provider actively monitors Visa and Mastercard chargeback program thresholds and alerts you before you breach them, rather than freezing your account after the fact.
What is a High-Risk Merchant Account Instant Approval Provider?
A high-risk merchant account instant approval provider is a payment processing company that specializes in approving and onboarding high-risk businesses—fast.
They’re built to handle industries banks usually avoid, like CBD, adult entertainment, credit repair, supplements, and more.
These providers cut through the usual red tape, offering payment processing solutions designed for high-risk transactions, higher chargeback rates, and complex business models.
Their main job: help you accept credit cards and other payments, often with same-day or next-day approval, plus tools to fight fraud and manage chargebacks.
If your business keeps getting turned away by “normal” payment processors, these are the firms you call. managing high chargeback rates and ensuring secure payment processing.
How to Choose Instant Approval High-Risk Merchant Account Services
Choosing a provider for instant approval high-risk merchant account services takes more than clicking the first “apply now” button you see. Use this table to break down the process and make your choice with eyes wide open:
| Step | What to do | Why it matters |
|---|---|---|
| Step1. Pinpoint your pain points | What to doList your deal-breakers: high chargeback rates, regulatory scrutiny, global sales, or industry bans. | Why it mattersOnly a provider who actually solves your headaches is worth the extra fees. |
| Step2. Demand true instant approval | What to doAsk exactly how long their “instant” is, and what paperwork you’ll need for underwriting. | Why it mattersAvoid getting stuck in a days-long approval “review”—clarity up front saves time. |
| Step3. Audit fees and contract traps | What to doRequest a full fee schedule, and flag hidden costs like rolling reserves, early termination, or support upcharges. | Why it mattersPrevent nasty surprises and lock-ins that drain your margins. |
| Step4. Test real-world integration and support | What to doPush for a real demo—run through your ecommerce flow, and call support after-hours. | Why it mattersIf they flinch, their tech or service may not hold up when you need it most. |
| Step5. Verify their track record | What to doCheck third-party reviews for payout delays, account holds, or surprise shutdowns—look for patterns, not marketing claims. | Why it mattersA bad reputation means your cash (or your business) could be at risk. |
Key Services to Look for in High-Risk Merchant Account Instant Approval Providers
Every provider promises the world, but you need services that make life easier for high-risk, high-volume, or regulated businesses.
Here’s what should actually matter when you’re comparing instant approval high-risk merchant account services:
- Real-time underwriting (not just “instant” in the marketing). You want a provider with a true instant approval process—automated, transparent, and designed for high-risk businesses. That means fewer manual reviews and faster access to credit card processing, even for adult entertainment, CBD, or nutraceuticals.
- Chargeback defense that works. Don’t settle for generic dispute tools. Look for payment processing solutions with automated alerts, deep chargeback analytics, and human backup to help you fight fraud and keep your merchant account alive.
- Rolling reserve transparency. If a payment processor is holding your cash as a rolling reserve, you need clear terms up front. How long, how much, and what it’ll take to reduce the reserve—no games, no moving targets.
- Support for “taboo” payment types. If your business handles high-risk transactions—crypto, ACH, cross-border, or emerging payment gateways—your merchant service provider should welcome that complexity and make it seamless, not a compliance headache.
- Customizable risk controls and reporting. The best high-risk merchant account providers let you set transaction limits, flag unusual activity, and pull real-time reports, so you can spot trends before they turn into problems.
- Seamless ecommerce and multichannel integrations. Whether you’re selling online, via mobile, or at a trade show, you want payment processing services that just work—with Shopify, WooCommerce, WordPress, or whatever else your stack includes.
- Industry-specific compliance and guidance. The right partner doesn’t just process payments—they help you stay compliant with PCI DSS, KYC, and any rules unique to your high-risk category. Expect proactive guidance, not generic warnings.
- Fast, predictable payouts (even for high volume or bad credit). Look for next-day or even same-day funding for high-risk merchants. You shouldn’t have to wait a week to access your own money, no matter what your business model or credit score.
Don’t waste time with providers who gloss over these details.
Benefits of Using Instant Approval High-Risk Merchant Account Services
Why bother with an instant approval high-risk merchant account provider? Here’s what you actually gain—beyond the basics.
- You start taking payments sooner. Fast approvals mean less downtime and fewer missed sales, even if your industry makes banks nervous.
- Less time wrestling with compliance. The right payment processors handle the heavy lifting on documentation, risk checks, and underwriting—so you can get approved with minimal back-and-forth.
- Built-in fraud and chargeback management. High-risk merchant account providers offer specialized tools to spot suspicious activity, reduce chargebacks, and keep your account in good standing.
- Global reach, without the roadblocks. Accept payments in multiple currencies and from high-risk regions, so your business can scale without outgrowing your merchant services.
- Support that actually shows up. When there’s a payout delay or sudden account freeze, you need real customer support—ideally, 24/7, with actual humans who know high-risk payment processing.
- Clarity on fees and reserves. You get upfront terms on rolling reserves, processing fees, and reserve release timelines—no more guessing what’ll hit your cash flow.
- Room to grow. The right high-risk payment processor adapts to your business model, whether your volume spikes, you expand to new categories, or your risk profile shifts.
Costs & Pricing Structures of High Risk Instant Approval Merchant Account Services
Here’s what real-world pricing looks like for high-risk merchant account services. Use these ranges to get your bearings—actual costs will vary by provider, industry, and volume.
| Plan type | Average price | Common features | Best for |
|---|---|---|---|
| Plan typeSubscription | Average price$10–$50/month | Common featuresMonthly maintenance, support tiers, basic fraud tools | Best forConsistent higher-risk sellers |
| Plan typeTransaction-based | Average price~3.5%–4% + $0.25/transaction | Common featuresPay per sale, integrated fraud/chargeback tools | Best forVariable or low-volume merchants |
| Plan typeTiered pricing | Average priceVaries (higher than standard) | Common featuresTiered rates (qualified/mid/non-qualified), bundled fees | Best forComplex or highly regulated operations |
| Plan typeCustom pricing | Average priceNegotiated per business | Common featuresTailored rates, rolling reserve terms, custom integrations | Best forUnique or very high-risk business models |
Key factors that influence high‑risk merchant account pricing
Pricing isn’t just numbers—it reflects your risk, setup, and flexibility. Here’s what pushes costs up or down:
- Your industry and risk profile. CBD, adult, nutraceuticals, or anything flagged high risk? Expect higher rates and reserves.
- Processing volume and track record. Clean history and volume can get you a better deal.
- Rolling reserve policy. Typically a portion (5–15%) of funds held as a buffer. Less transparent terms mean more risk to your cash flow.
- Contract length and fees. Watch for auto-renewals, early termination penalties, and hidden costs.
- Support and integrations. 24/7, industry-aware support or complex integrations (multichannel, crypto) often carry a premium.
Understanding these levers helps you negotiate smarter and avoid surprises when funds hit your account—or don’t.
FAQs About High-Risk Merchant Account Instant Approval Services
Here are some answers to common questions about high risk merchant account instant approval:
Will “instant approval” really get my account live today?
Not usually. “Instant approval” means you get a fast preliminary decision—sometimes in minutes—but you’ll still need to complete underwriting before you can process payments. If your documents are ready and your business checks out, most providers can get you set up in 24–72 hours.
What will providers look for in my application?
Expect to provide business licenses, a valid ID, recent bank statements, processing history (if any), and details on your business model. High-risk processors are extra thorough—they want to see you’re legitimate and have processes for handling chargebacks and refunds.
How do rolling reserves actually work?
A rolling reserve is a percentage of your sales held back (usually 5–15%) for a set period (commonly 90–180 days) to cover potential chargebacks or fraud. Good providers tell you the terms up front, so ask for details in writing.
What happens if I get too many chargebacks?
Too many chargebacks can mean higher fees, a spike in your rolling reserve, or even account termination. Most high-risk payment processors have built-in alerts and chargeback mitigation tools, but if rates get too high, you might need to move fast to another provider.
Can I negotiate lower fees once I’ve proven myself?
Yes. If you keep your chargebacks low and grow your processing volume, many providers are open to lowering your rates or relaxing reserve requirements. Don’t be afraid to ask for a better deal after six months of clean history.
What should I do if my account is frozen or shut down?
First, get a straight answer from your provider about why it happened. You’ll need to resolve the issue—whether it’s too many chargebacks, compliance flags, or missing documents—before you can get unfrozen. Have a backup processor on speed dial just in case; downtime kills cash flow.